This is one of the most asked questions in crypto and one of the most consistently badly answered, because almost everyone — on both sides of the argument — misunderstands what SWIFT does.
Getting the distinction right does not just make the answer more accurate. It changes which competitive threat actually matters, and reveals a development that has been happening in plain sight.
What SWIFT actually is
SWIFT is a messaging cooperative. It connects more than 11,000 financial institutions across over 200 countries, and what travels across it is instructions — standardised messages telling one bank what another bank wants done.
It does not hold your money. It does not move your money. It does not settle anything.
ISO 20022 standardises how payment instructions are communicated. It does not process the money. That requires settlement infrastructure, which SWIFT historically did not provide.
That standard became the norm for cross-border payment instructions on 22 November 2025, with adoption reaching roughly 97% of payment instructions shortly after. It is a genuine achievement in financial plumbing — and it is still just a common language for messages.
The actual movement of value happens through correspondent banking: a chain of banks holding accounts with each other, passing balances along, each taking a fee and adding a delay. That chain is what makes a cross-border payment take days and cost 3–7%. SWIFT is the messaging that coordinates it.
So what do stablecoins actually replace?
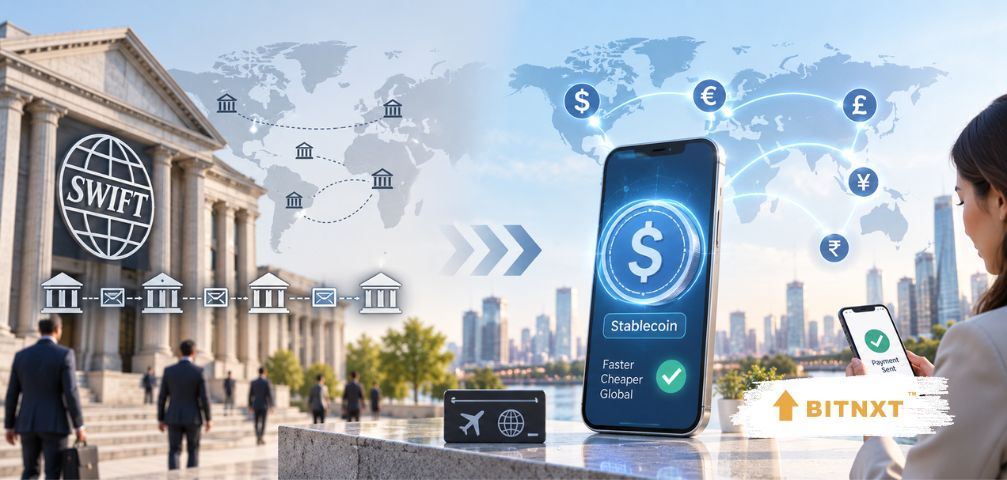
Correspondent banking. Not SWIFT.
The dominant enterprise pattern is fiat to stablecoin to fiat: the sender pays in local currency, value moves on-chain, the recipient is paid out in their own currency. Neither party necessarily holds a token. Settlement takes minutes rather than days, at roughly 0.5–2.5% total cost against 3–7% for correspondent banking.
What has been removed there is the intermediary chain — the nostro accounts, the pre-funding, the cut-off times, the three banks each taking a cut. The messaging layer is not the thing being disintermediated. It is the settlement layer underneath it.
Layer | Traditional | Stablecoin rail |
|---|---|---|
Instruction / messaging | SWIFT, using ISO 20022 | Transaction data on-chain, plus the payment provider’s own APIs |
Settlement | Correspondent banking chain with nostro accounts and pre-funding | On-chain transfer of a tokenized dollar |
Speed | Days, constrained by cut-off times and weekends | Minutes, continuous |
Cost | Roughly 3–7% | Roughly 0.5–2.5% |
What is disrupted | — | The middle row, not the top row |
So the properly framed question is: will stablecoins replace correspondent banking? And the honest answer there is that they are taking share in specific corridors while remaining under 1% of global cross-border payment volume against a total addressable market estimated above $17.9 trillion.
The part nobody noticed: SWIFT built a settlement layer
Here is the development that actually answers the headline question, and it has had a fraction of the coverage the stablecoin narrative gets.
THE SWIFT SHARED LEDGER September 2025 — announced at Sibos: a blockchain-based shared ledger for instant, round-the-clock cross-border payments. Design phase — input from more than 30 banks including JPMorgan, HSBC, Deutsche Bank and BNP Paribas. 30 March 2026 — design stage completed, moving to a first Minimum Viable Product. Mid-2026 — the ledger goes live, with the group narrowed to a 17-bank pilot. Built by ConsenSys on Linea, an Ethereum layer-2 using zero-knowledge proofs, on an EVM-compatible model based on Hyperledger Besu. |
Read that again. The incumbent everyone assumed would be disrupted by blockchain has deployed a blockchain, built by the company behind MetaMask, on an Ethereum layer-2.
The design is deliberate and worth understanding. It is not a public chain and there is no native cryptocurrency. It is permissioned — the bank consortium controls who can transact. It is token-agnostic, designed to move tokenized deposits, regulated stablecoins, CBDCs and tokenized funds across institutions in real time. Smart contracts record, sequence and validate transactions while ISO 20022 carries the compliance data.
In other words: SWIFT kept its messaging standard, kept its membership, kept regulatory control, and bolted on the settlement capability it never had. HSBC and Standard Chartered both pointed to faster liquidity visibility and fewer reconciliation delays as the main draw for corporate clients.
The criticism
The permissioned design draws obvious scrutiny. A ledger where an incumbent consortium decides who may transact preserves exactly the gatekeeping that made stablecoins attractive in the first place. If your problem is that correspondent banks are slow and expensive, a faster ledger run by the same correspondent banks solves half of it.
And scale still lags. A pilot with 17 banks is not a settlement network handling meaningful volume, while stablecoin rails already process hundreds of billions in real payments annually.
Three plausible futures
Scenario | What happens | Evidence for it |
|---|---|---|
Displacement | Stablecoin rails take an increasing share of cross-border flows; SWIFT messaging becomes less relevant as settlement moves entirely on-chain. | B2B stablecoin payments grew roughly 733% in a year. Stripe, Visa and PayPal shipped production integrations. Corridors in Asia and the Gulf are already meaningful. |
Coexistence | Banks gain speed and visibility through tokenized rails while keeping control of keys, compliance and settlement. Both systems run in parallel and institutions choose per transaction. | SWIFT has said explicitly that the ledger runs alongside upgrades to existing fiat rails. This is the mainstream institutional expectation for 2026–27. |
Absorption | SWIFT’s ledger becomes the settlement venue for regulated tokens, including bank stablecoins and tokenized deposits. Stablecoins win the technology argument; incumbents keep the customers. | The ledger is explicitly token-agnostic and built to carry regulated stablecoins. Twenty-one banks are separately building their own dollar token. |
The third is the most under-discussed and, on current evidence, the most likely. It is what usually happens to financial infrastructure: the new technology wins, and the incumbent institutions run it.
What each side is genuinely better at
Stablecoin rails win on cost, speed, availability and reach into markets where correspondent relationships are thin, expensive or absent. They also serve counterparties banks will not onboard — including, increasingly, software.
SWIFT and the banking system win on regulatory acceptance, dispute resolution, sanctions screening at scale, credit relationships and the simple fact that a corporate treasurer already has an approved process for using them.
Neither currently wins on interoperability. A stablecoin payment still needs off-ramps at both ends; a permissioned ledger still needs everyone to join it.
The prize is large enough for both. Cross-border payment volumes have been estimated at around $194.6 trillion in 2024, projected to reach roughly $320 trillion by 2032. Stablecoins do not need to displace SWIFT to build an enormous business; they need to keep taking the flows correspondent banking handles worst.
What to watch
Whether the SWIFT ledger moves beyond 17 banks. Pilot to production is where most bank consortium projects stall.
What settles on it. If regulated stablecoins and bank tokens start moving across the SWIFT ledger, the absorption scenario is confirmed.
The sub-1% cross-border share for stablecoins. That single ratio is the cleanest measure of whether displacement is happening.
Whether permissioning loosens. A ledger that admits non-bank payment providers would be a materially different competitive proposition.
Corridor-level data. National-level adoption in specific routes will show the shift long before global aggregates do.
The bottom line
Stablecoins will not replace SWIFT, because SWIFT is a messaging standard and stablecoins do not send messages. What stablecoins are genuinely eroding is correspondent banking — the slow, expensive intermediary chain that SWIFT messages coordinate.
The more interesting development is that SWIFT reached the same conclusion earlier than most commentators. Rather than defend correspondent settlement, it built a permissioned Ethereum layer-2 ledger capable of moving tokenized deposits, CBDCs and regulated stablecoins around the clock — and put seventeen banks on it.
So the likely outcome is not stablecoins versus SWIFT. It is tokenized settlement winning, and the argument being about who operates it: a permissioned consortium of incumbents, or open rails that anyone can build on. That is a fight about governance, not technology — and it is the one worth following.
Important
This article is general information and market analysis. It is not investment, financial or legal advice. Figures are drawn from third-party research and company disclosures and reflect the periods stated; definitions of payment “volume” differ between sources and are not directly comparable. Projects described are at pilot or MVP stage and may change, expand or not proceed.
Sources
SWIFT and ConsenSys announcements and pilot disclosures, ISO 20022 migration data, J.P. Morgan cross-border volume estimates, McKinsey and Artemis Analytics payment research, FXC Intelligence market sizing, plus reporting from Forbes, BeInCrypto, CCN and Yahoo Finance.
Bitnxt tracks stablecoin issuers, payment gateways and licensed service providers across the US, UK, EU and UAE. Explore the directory at bitnxt.io.