The first principle
Stablecoins do not generate yield. A dollar-pegged token in a wallet produces nothing at all.
Every advertised return traces back to someone paying for access to capital: a borrower paying interest, a trader paying fees, or a government paying coupon on its debt. There is no fourth option and no magic.
The source is the risk. If you cannot name who is paying you, you cannot assess what happens when they stop.
That framing does most of the work in this article. Advertised APYs in 2026 span roughly 4% to 15%, and the spread is not a reward for cleverness — it reflects genuine differences in who the payer is, how reliably they can keep paying, and what happens to your capital if they cannot.
Source one: reserve income — and the uncomfortable answer
This is the largest and least understood source, so it is worth being precise about it.
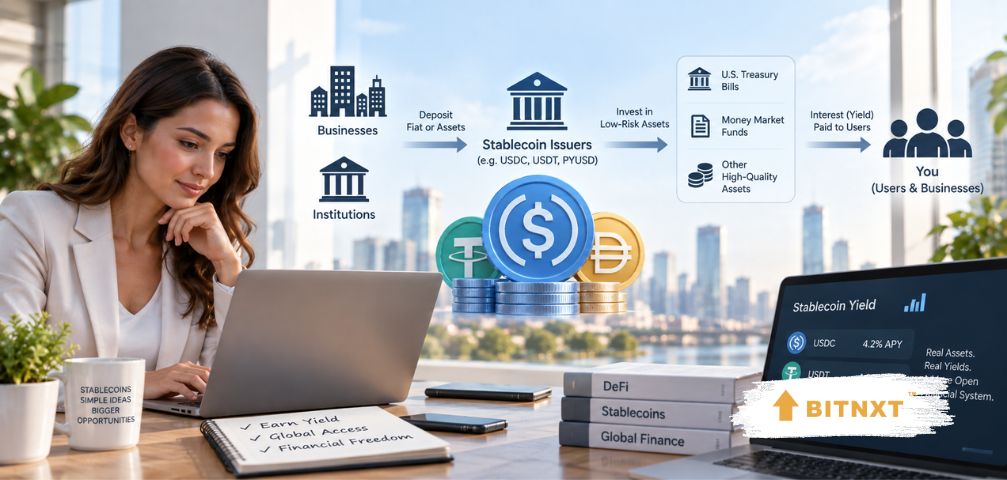
When you buy a stablecoin, you hand over a dollar. The issuer takes that dollar and buys short-duration Treasury bills and repo. Those instruments pay interest. Research from the Bank for International Settlements documents that this reserve interest is the substrate of the entire stablecoin economy — and with total stablecoin float crossing roughly $315 billion in mid-2026, that reserve income now rivals a mid-sized money market complex.
So who pays the interest? In the first instance, the US government, through T-bill coupons. Three-month bills were yielding around 3.65% in May 2026, with the federal funds rate anchoring the risk-free floor near 4.25%.
But follow it one step further and the answer becomes more interesting.
THE PART NOBODY SAYS OUT LOUD You gave the issuer a dollar. The issuer earns roughly 4% on it. You earn nothing on the token itself. Any “reward” a platform pays you is a partial rebate of the interest being earned on your own float. The question is not who is generously paying you. It is what share of your own money’s earnings you are getting back. |
That is the honest mechanic behind exchange rewards programmes. The issuer earns reserve income, shares part of it with the distribution platform, and the platform passes part of that on to you. Each layer keeps a cut. If T-bills pay around 4% and you receive around 4%, the platform is running the programme at close to break-even as an acquisition cost — which tells you the balance itself is the product being bought.
It also explains why this became a legislative fight. Reserve income at scale is a very large revenue pool, and the argument over who may pass it to whom is an argument about that pool.
Source two: borrowers
In on-chain lending markets, the payer is straightforward: someone borrowing against collateral, paying interest for the privilege.
Typical returns run roughly 1.8% to 5% on major lending protocols, and the rate is a direct function of borrowing demand. When leverage demand is high, lending rates rise; when it collapses, so does your yield.
The important thing to understand is what you have become. You are not a depositor — you are a lender. Your return depends on borrowers staying solvent, on liquidation mechanisms working during volatility, and on the protocol’s code being sound. Overcollateralisation makes this reasonably robust in normal conditions and is not a guarantee in disorderly ones.
Source three: traders paying fees
Providing liquidity to a decentralised exchange earns a share of trading fees. The payer is whoever is trading through that pool.
This is real revenue from real activity, but it carries a risk that is unique to the category: the value of your position can diverge from simply holding the assets, depending on how prices move while you are providing liquidity. Stablecoin-to-stablecoin pools reduce that materially, which is why they are the common choice for conservative allocators — but the yield is correspondingly thinner.
Source four: leveraged long traders
This is the source behind the double-digit numbers, and it deserves careful explanation because it is the least intuitive.
The best-known example is Ethena’s synthetic dollar. For every dollar minted, the protocol holds roughly a dollar of long crypto exposure — primarily liquid-staked ETH and spot BTC — while simultaneously shorting the equivalent in perpetual futures on centralised exchanges. The position is delta-neutral: it does not care much which way the price moves.
The return comes from two places. The staked ETH on the long leg earns roughly 3–4%. And on the short leg, the protocol collects the perpetual funding rate paid by leveraged long traders.
So the answer to “who pays the interest” here is unusually literal: traders using leverage to bet on crypto going up. Their funding payments are your yield.
That has an obvious implication. When markets are bullish and leveraged long demand exceeds short demand, funding is positive and the yield is generous. When enthusiasm compresses or inverts, the yield falls fast. Bitcoin funding rates averaged roughly 11% annualised in 2024 and around 5% by 2025. The staked variant of Ethena’s dollar showed a 90-day trailing average around 11.8% in April 2026, having dropped to 3–4% during compressed periods.
There is also a structural detail worth knowing: only the staked version earns. Holders of the unstaked token forgo yield in exchange for using it as collateral without lockup, and the ratio between the two — around 55% staked in early 2026 — is effectively a confidence gauge on the yield leg.
Source five: protocol surplus
Some protocols pay a savings rate funded from their own treasury surplus, which ultimately derives from one of the sources above — typically lending revenue and Treasury holdings. Returns here have run around 3.5%.
This is a legitimate source but an indirect one. You are relying on the protocol continuing to generate surplus and continuing to choose to distribute it. Governance can change that.
And the one that is not a source at all
Token incentives — rewards paid in a protocol’s own token to attract deposits — sit on top of genuine yield as a temporary subsidy, not a durable source.
If an advertised APY is substantially made up of emissions, you are being paid in something whose value depends on continued demand for the token, funded by dilution. That can be perfectly rational to farm with eyes open. It is not interest, and treating it as interest is how people end up surprised.
The ladder, with payers named
Source | Who actually pays | Typical 2026 range | Fails when |
|---|---|---|---|
Tokenized Treasuries | The US government, via T-bill coupons | Roughly 3.5–5.3% | Rates fall. Also issuer solvency and redemption gates. |
Regulated platform rewards | The issuer, rebating part of reserve income | Roughly 4–5% | Rates fall, or regulation restricts the rebate. |
Overcollateralised lending | Borrowers taking leverage | Roughly 1.8–5% | Borrowing demand collapses, or liquidations fail in volatility. |
DEX liquidity provision | Traders paying swap fees | Varies widely by pool | Volume dries up; position value diverges from holding. |
Basis trade / synthetic dollars | Leveraged long traders paying funding | Roughly 4–15%, highly variable | Funding rates compress or invert. Exchange counterparty risk. |
Protocol savings rates | The protocol’s surplus revenue | Around 3.5% | Surplus disappears, or governance redirects it. |
Token emissions | Dilution of existing holders | Advertised high | Immediately, once emissions stop or the token falls. |
A useful reference point: tokenized Treasury funds have largely replaced parking capital in a lending pool as the conservative default, with BlackRock’s tokenized fund at around $3.0 billion in assets. When the safest tier pays 4% and something advertises 12%, the difference is not efficiency — it is a different payer with a different failure mode.
Why the legal distinction matters
One structural point that shapes the whole market: the US framework draws a hard line between the stablecoin wrapper itself and third-party protocols that generate yield using that wrapper.
The issuer is restricted in what it may pay holders for simply holding the token. Separate protocols that take the token and deploy it into lending, liquidity or basis strategies are a different legal matter entirely. That distinction is why the market has organised itself the way it has — with the yield-bearing layer sitting adjacent to the stablecoin rather than inside it.
It also means that when you read about restrictions on stablecoin yield, you need to check which layer is being restricted. Rules aimed at issuers do not automatically reach protocols, and vice versa.
Questions worth asking before accepting a yield
Who is the payer? If the marketing does not name them, treat that as the answer.
What rate regime does this depend on? T-bill products suffer if the Fed cuts; basis-trade products suffer if funding inverts. Those are different exposures, and holding both is diversification.
How much of the advertised APY is emissions? Strip those out and look at the underlying rate.
Where does my capital sit? Custodial platform, smart contract, or a fund structure — each has a different failure mode and a different recovery path.
What is the redemption path under stress? Gates, minimum sizes and allowlists matter far more on a bad day than on a normal one.
Am I being paid for risk or for float? A rebate on your own reserve income is not the same proposition as lending into a market.
The bottom line
Who pays the interest on stablecoins? Depending on the product: the US Treasury, leveraged crypto traders, borrowers in lending markets, people swapping tokens, a protocol’s surplus, or existing tokenholders through dilution.
For the largest category — reserve-backed stablecoins — the honest answer is more pointed. The interest is being earned on your dollar, by someone else, and what you receive is a share of it handed back. That is not a criticism of the model; it is how money market funds and bank deposits have always worked. But it does reframe the question from “how generous is this platform” to “how much of my own float’s earnings am I keeping”.
Sustainable stablecoin yields in 2026 cluster around 3–6% because that is roughly what real economic activity supports. Anything materially above that is not a better product — it is a different payer, with a different reason they might stop.
Important
This article is a general educational explainer. It is NOT investment, financial or tax advice, and nothing here is a recommendation to use any platform, protocol or product. Yields cited are indicative ranges from third-party research at the dates stated and change constantly. Stablecoin yield strategies carry real risk of permanent capital loss — smart contract exploits, liquidation cascades, exchange counterparty failure and depeg events have all caused losses. Higher advertised returns reflect higher risk, not superior technology. Regulatory treatment varies by jurisdiction and product. Do your own research and consider taking professional advice before committing capital.
Sources
Bank for International Settlements research on stablecoin reserves, DefiLlama float data, plus analysis and rate data from Eco, Spark, Messari, RedStone, CoinDesk, crypto.news, Altrady and Investax covering the periods described.
Bitnxt tracks stablecoin issuers, lending platforms and licensed service providers across the US, UK, EU and UAE. Explore the directory at bitnxt.io.