Depending on which number you cite, stablecoins settled $33 trillion last year or $390 billion. Both are correct, and the gap between them is the whole story. Here is what stablecoins have actually replaced, where the adoption is real, and why “the internet’s payment layer” is the wrong description of what is happening.
Three numbers, all true
Any serious discussion of stablecoin payments has to start by acknowledging that the headline figures measure completely different things.
Figure | What it measures | Why it differs |
~$33 trillion (2025) | Total on-chain stablecoin transaction volume, up roughly 72% year on year. | Includes trading, arbitrage, bot activity, internal exchange transfers and automated movements. It is a measure of chain activity, not commerce. |
~$9–11 trillion annualised (early 2026) | Visa’s on-chain analytics estimate of “organic” volume, stripping out bot trades, MEV and internal exchange transfers. | A much stricter filter. At this level, stablecoin throughput already rivals Mastercard’s full annual volume. |
~$390 billion (2025) | Actual end-user payment activity — B2B transfers, payroll, remittances, capital markets settlement. | The commerce number, per McKinsey and Artemis Analytics. More than double the prior year. |
Anyone telling you stablecoins have overtaken Visa is quoting the first number. Anyone telling you stablecoin payments are irrelevant is quoting the third. The useful analysis lives in what the third number is made of.
What is actually growing: B2B, and not the part you would guess
Business-to-business settlement accounts for roughly 60% of all real stablecoin payment volume — approximately $226 billion in 2025, up around 733% year on year.
The composition matters more than the growth rate. Adoption is being driven by manufacturing, commodity trading and logistics, not by crypto-native firms. Monthly B2B volume moved from under $100 million in early 2023 to over $6 billion by mid-2025, roughly a sixtyfold increase in thirty months.
That is the detail that separates this cycle from previous stablecoin narratives. A 733% increase in B2B payments means treasury teams and CFOs at ordinary companies are choosing stablecoins for operational settlement. Those are not people who buy a narrative; they are people who compare a fee schedule.
The mechanism: the sandwich
Most enterprise stablecoin payments never touch a wallet the sender or receiver manages. The pattern is fiat to stablecoin to fiat — the sender pays in local currency, the value moves on-chain, and the recipient is paid out in their own currency. Neither party necessarily holds a token at any point.
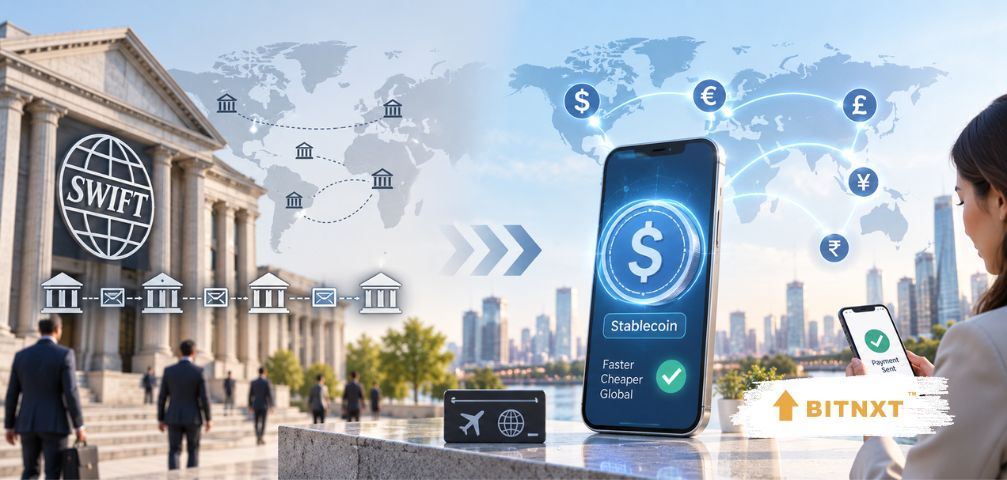
The economics are straightforward: settlement in minutes rather than days, at roughly 0.5–2.5% total cost against 3–7% for correspondent banking. Stablecoins are not competing with the dollar here. They are competing with the correspondent banking network — a chain of intermediaries, cut-off times, and pre-funded nostro accounts that has barely changed in forty years.
Where the volume actually is
Region | Share of global stablecoin payment volume |
Asia-Pacific | Around 60%, roughly $245 billion, concentrated in Singapore, Hong Kong and Japan |
North America | Around 23%, roughly $95 billion, anchoring investment and regulatory development |
Europe | Around 12% |
Active corridors | Turkey to UAE, UAE to Southeast Asia, and Mexico to US all showing significant growth |
This distribution is the most under-reported fact in the sector. Stablecoin payments are not primarily an American phenomenon with global spillover — the majority of real volume originates in Asia, in corridors where the delta against correspondent banking is widest.
It also explains why adoption looks slow from a Western vantage point. If you are settling euros to dollars between two banked counterparties in developed markets, stablecoins save you very little. If you are moving value between markets where correspondent relationships are thin, expensive or slow, they save you a great deal.
The institutions stopped experimenting
The strongest evidence that this is infrastructure rather than a pilot is who is now running it in production.
Stripe acquired stablecoin infrastructure provider Bridge for $1.1 billion in late 2024 and launched stablecoin payment acceptance for merchants across more than 100 countries during 2025.
Visa launched USDC settlement in December 2025 and reported roughly $4.5–4.6 billion in annualised stablecoin settlement volume by early 2026, with card-linked programmes letting holders spend USDC at merchants globally without converting first.
PayPal’s PYUSD grew around 600% through 2025 to roughly $3.6 billion in circulation.
Mastercard, Fiserv and Western Union have all announced stablecoin integration programmes.
The Visa card-linked detail deserves emphasis. It means the stablecoin sits behind the existing card rails rather than replacing them — the merchant sees a normal card transaction. That is how payment infrastructure actually gets adopted: invisibly, underneath an interface nobody has to relearn.
What unlocked it
The change between 2024 and 2026 was not technical. The rails worked before. What changed is that the regulatory ambiguity blocking enterprise adoption largely dissolved.
THE REGULATORY UNLOCK
GENIUS Act, signed July 2025 — the first US federal framework for payment stablecoin issuers, covering reserves, redemption and AML.
MiCA — fully applicable across the EU, with the transitional period for service providers ending 1 July 2026.
Hong Kong — enacted its Stablecoin Bill, adding a major Asian jurisdiction with a defined regime.
UK — FCA rules finalised, with the authorisation gateway opening 30 September 2026 and the regime commencing October 2027.
No corporate treasurer signs off on an unregulated settlement asset. Once issuance is licensed, reserves are defined and redemption is a legal obligation, the internal approval conversation changes completely — from “can we use this” to “does it cost less”.
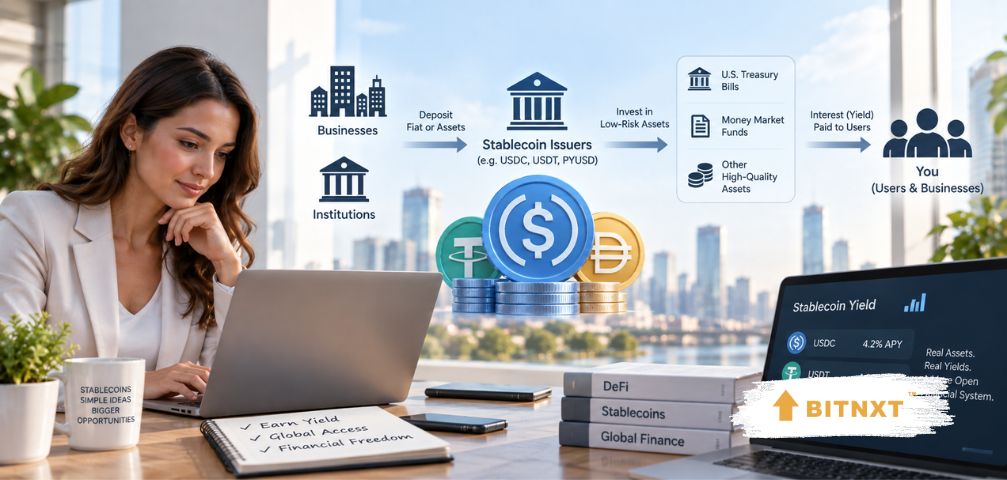
One consequence worth noting: stablecoin issuers held roughly $155 billion in US Treasuries. The payment layer is now a meaningful buyer of government debt, which is why this stopped being purely a payments story and became a monetary one — and why the ECB has resisted opening the EU to third-country issuers.
The ceiling, stated honestly
Now the part the sector’s own marketing leaves out.
Stablecoin cross-border payments represent a total addressable market of upwards of $17.9 trillion, according to FXC Intelligence. Current volume is less than 1% of global cross-border payment transaction volume.
Read those two sentences together. After the fastest growth in the sector’s history, after Stripe, Visa, PayPal and Mastercard all shipped production integrations, after three major jurisdictions passed enabling legislation — stablecoins handle under one percent of the flows they are best suited to.
Projections for where it goes vary widely and should be treated as scenarios rather than forecasts. The US Treasury has projected stablecoin supply reaching $3 trillion by 2030, with institutional estimates ranging from around $1.9 trillion in a base case to $4 trillion in aggressive scenarios. Industry forecasts put stablecoins at 5–10% of all cross-border payments by 2030.
Supply itself has grown steadily rather than explosively: roughly $124 billion at the end of 2023, around $205 billion a year later, approximately $310 billion by mid-2026, with projections near $420 billion by year-end. USDC and USDT together accounted for roughly $267 billion of circulating supply in April 2026.
So is it “the internet’s payment layer”?
Not in the sense the phrase implies, and the distinction is worth being precise about.
The internet’s consumer payment layer is still cards, wallets and bank transfers. Nobody is buying groceries with USDC at scale, and the Visa card-linked model suggests they will not need to — the stablecoin will sit underneath, invisible.
What stablecoins have genuinely become is the settlement layer for a specific and large class of flows: cross-border business payments, emerging-market dollar access, on-chain treasury operations, and now machine-to-machine payments where no bank will onboard the counterparty.
That is not the internet’s payment layer. It is something more specific and arguably more durable — the layer that handles the payments the existing system handles worst.
Which is how infrastructure usually wins. Not by replacing the incumbent everywhere, but by taking the segments where the incumbent is weakest and compounding from there.
What to watch
Whether real payment volume keeps roughly doubling. The $390 billion figure is the only number that matters; growth in the $33 trillion figure tells you nothing about commerce.
Non-dollar stablecoins. Almost all of this is dollar-denominated, which is why the ECB treats it as a sovereignty issue. Meaningful euro or sterling volume would change the political calculus.
Whether the sub-1% cross-border share moves. That single ratio is the cleanest measure of whether adoption is compounding or plateauing.
Yield rules. Whether platforms can pay holders a return is being fought over in the US and constrained in the UK, and it materially changes the economics of holding balances.
Agentic payments. Currently negligible in volume terms, but the one category where there is no alternative rail at all.
The bottom line
Stablecoins have crossed from experimental adoption into infrastructure adoption. The evidence is not the trillion-dollar headline figures — it is that manufacturers, commodity traders and logistics firms are settling supplier invoices with them, and that Stripe, Visa and PayPal built production systems around them.
But the honest scale is a $390 billion real-payments market inside a $17.9 trillion opportunity, running at under one percent penetration. This is early infrastructure with genuine product-market fit in specific corridors, not a completed transition.
The right mental model is not that stablecoins are replacing the payment internet. It is that a parallel settlement rail has been built, it is now licensed in the major jurisdictions, and it is winning exactly the flows the old rail handles badly. Whether that stays a niche or becomes the default depends on the next five years of that sub-one-percent number.
Important
This article is general information and market analysis. It is not investment, financial or legal advice. Figures are drawn from third-party research including McKinsey, Artemis Analytics, Visa, FXC Intelligence and company disclosures, and reflect the periods stated — definitions of “volume” differ significantly between sources, so figures from different providers are not directly comparable. Projections cited are scenarios published by their authors, not outcomes. Stablecoins carry issuer, reserve, regulatory and operational risks.
Sources
Research and data from McKinsey and Artemis Analytics, Visa on-chain analytics, FXC Intelligence, BCG and Allium Labs, Citi Treasury Services, DeFiLlama, TRM Labs and Juniper Research, plus company disclosures from Stripe, Visa, PayPal and Circle, and regulatory materials covering the GENIUS Act, MiCA and the FCA regime.
Bitnxt tracks stablecoin issuers, payment gateways and licensed service providers across the US, UK, EU and UAE. Explore the directory at bitnxt.io.