





























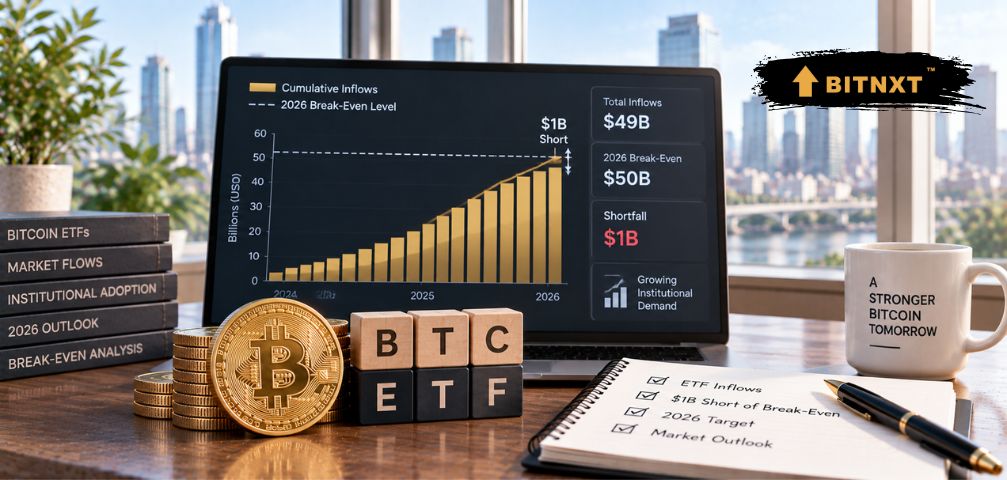
U.S. Bitcoin ETF investors have shoveled $1.59 billion back into the funds since August, and the 2026 ledger still shows red. Cumulative net flows for the year sit roughly $1 billion below break-even, per SoSoValue data, meaning every dollar of the summer rebound has been absorbed repairing damage that June did. Bitcoin traded at $78,239.89, up 1.73% on the day, while the funds that supposedly institutionalized this market spent the year giving money back.
The paradox is worth sitting with. Price is up. Flows are negative. The 12 spot funds that opened 2026 as the story of crypto's Wall Street arrival have, on net, seen investors pull more than they put in, and the recovery rally from the summer lows near $63,000 ran substantially on derivative repositioning and spot short-covering rather than fresh ETF balance-sheet allocation. When the primary institutional wrapper bleeds while the asset rallies, you are watching a market carried by leverage and conviction holders, not by the marginal pension dollar.
The Bitcoin ETF Flow Math Since June
June is the wound. Net outflows hit $1.51 billion that month, enough to wipe out the cumulative inflows of March and April combined, and the deficit's origin is almost entirely that stretch of institutional redemptions. August answered with the strongest month of the year: $1.52 billion in fresh inflows. September has added $70.15 million month-to-date. Add it up and the funds remain about $1 billion shy of where January started them, a gap that needs several more August-sized prints to close. It is the mirror image of January's euphoria, when a single $731 million day marked the year's biggest inflow, and a reminder that even BlackRock's relentless buying streaks cannot outrun a redemption month on the other side of the ledger.
What makes the current stretch different is that inflows are arriving against a hostile macro backdrop. CME FedWatch pricing leans toward a hike at the September 15-16 FOMC, the same odds shift that traders repriced after the August jobs beat. Short-term Treasury yields remain elevated. Oil is doing no one any favors: Nymex WTI crude has surged 10% month-to-date, crossing a three-month high above $94 per barrel, energy costs that feed straight into headline CPI and hand hawks their favorite exhibit.
Thursday's CPI Decides Whether the Rebound Is Real
Bitfinex analysts frame the week cleanly: "The key test now is whether those inflows survive this week's CPI and Treasury buyback." Their second point is the more interesting one. "If investors continue buying while short-term yields remain elevated, it would indicate that the policy rate is no longer the binding constraint on bitcoin." That is the decoupling thesis in one sentence, and the ETF flow line is the only honest scoreboard for it. Positive daily prints through a hot CPI release and a hiking Fed would say institutions have stopped pricing Bitcoin off the two-year yield. A reversal says the June redemption class is still in charge, waiting for the macro to break their way.
Skepticism, briefly: $70 million in eight September days is not conviction, it is drift, and one hawkish CPI print would wipe it. The bulls' own math requires the funds to recover $1 billion before the year's flows mean anything at all.
Watch Thursday's CPI and the size of the daily ETF prints around it. Closing the year's flow gap before the FOMC would be the first hard evidence that this rally has institutional fuel rather than just thin-market momentum behind it.


