





























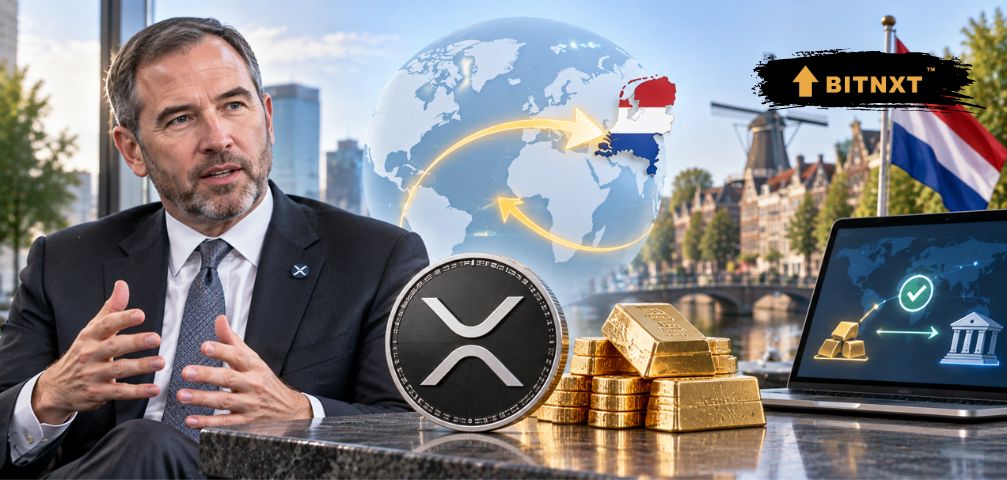
The Dutch central bank just spent five months moving 86 tonnes of gold across the Atlantic without changing its holdings by a single ounce, and Ripple's CEO thinks that is the best ad crypto never bought. De Nederlandsche Bank confirmed it sold 59 tonnes in New York, repurchased an identical 59 tonnes of market-standard bars in London, and shipped over 27 tonnes of physical bullion from North America to its cash center in Zeist, a pure liquidity play that moved the Bank of England's share of Dutch reserves from 18.1% to 32.1% while the New York Fed's share fell from 31.3% to 18.5%.
Brad Garlinghouse responded on X: "Why does financial value still depend on these location-centric processes?" His point is the one crypto has made for a decade: value that settles in minutes does not need barges, vaults and a five-month schedule. DNB Governor Olaf Sleijpen framed it from the other side: the bank "must remain prepared for severe conditions and ensure that part of the reserve can be traded when needed," which is why it optimized custody locations and upgraded to London-good-delivery bars.
What the Gold Shuffle Actually Proves
Both men are right, which is what makes the story worth reading carefully. Central banks do not move reserves for convenience; they move them for crisis optionality, the same instinct driving Germany's 2013-17 repatriation of 674 tonnes to Frankfurt. Gold's physicality is the feature for a central banker and the bug for a payments executive. A tokenized reserve moves in minutes, but it also inherits its network's failure modes, a tradeoff institutions price differently after the Liquid Network spent a weekend recovering 3,400 BTC.
Garlinghouse has skin in the argument. Ripple Payments has processed over $100 billion across 60-plus markets as of July 2026, and the XRP Ledger settles the kind of value transfer stablecoin rails now compete for. Germany's DZ Bank opening crypto trading for cooperative banks shows the institutional wall cracking. But the sales pitch has a familiar gap: the gold shuffle was slow because central banks want it slow, verifiable custody beats settlement speed when the asset backs a currency. Not every friction is waste; some is audit.
The test to watch: whether any central bank ever tokenizes even a sliver of reserves for settlement purposes, the way Brazil's state bank already buys tokenized notes. Until one does, Garlinghouse is selling a solution to institutions whose defining trait is preferring to hold the metal. The Dutch shuffle proves crypto's thesis and ignores it at the same time.


