















BTCBTC$76,919-1.76%|
ETHETH$2,252.36-1.67%|
USDTUSDT$0.99874-0.03%|
BNB$695.8000-2.29%|
XRPXRP$1.2500-0.38%|
USDCUSDC$0.99935-0.03%|
SOLSOL$92.0000-2.97%|
TRXTRX$0.32013+2.22%|
FIGR_HELOCFIGR_HELOC$1.0320+0.00%|
HYPEHYPE$83.8500-4.25%|
ZECZEC$1,138.54-9.09%|
DOGEDOGE$0.07411-1.89%|
XMRXMR$605.9500+0.32%|
USDSUSDS$0.99971-0.03%|
WBTWBT$73.8800-1.79%|
LEOLEO$9.3100-0.92%|
LINKLINK$11.0700-2.21%|
ADAADA$0.18866-2.41%|
XLMXLM$0.16162-4.45%|
BCHBCH$274.7600-3.02%|
NEARNEAR$3.8300-11.01%|
RAINRAIN$0.00674588+15.84%|
DAIDAI$0.99998-0.01%|
USDEUSDE$0.99799-0.05%|
UNIUNI$6.9100-4.28%|
LTCLTC$53.8400-3.49%|
USD1USD1$0.99677-0.11%|
CCCC$0.09340-3.25%|
AVAXAVAX$8.3500-3.44%|
SUISUI$0.86790-3.77%|
BTCBTC$76,919-1.76%|
ETHETH$2,252.36-1.67%|
USDTUSDT$0.99874-0.03%|
BNBBNB$695.8000-2.29%|
XRPXRP$1.2500-0.38%|
USDCUSDC$0.99935-0.03%|
SOLSOL$92.0000-2.97%|
TRXTRX$0.32013+2.22%|
FIGR_HELOCFIGR_HELOC$1.0320+0.00%|
HYPEHYPE$83.8500-4.25%|
ZECZEC$1,138.54-9.09%|
DOGEDOGE$0.07411-1.89%|
XMRXMR$605.9500+0.32%|
USDSUSDS$0.99971-0.03%|
WBTWBT$73.8800-1.79%|
LEOLEO$9.3100-0.92%|
LINKLINK$11.0700-2.21%|
ADAADA$0.18866-2.41%|
XLMXLM$0.16162-4.45%|
BCHBCH$274.7600-3.02%|
NEARNEAR$3.8300-11.01%|
RAINRAIN$0.00674588+15.84%|
DAIDAI$0.99998-0.01%|
USDEUSDE$0.99799-0.05%|
UNIUNI$6.9100-4.28%|
LTCLTC$53.8400-3.49%|
USD1USD1$0.99677-0.11%|
CCCC$0.09340-3.25%|
AVAXAVAX$8.3500-3.44%|
SUISUI$0.86790-3.77%|
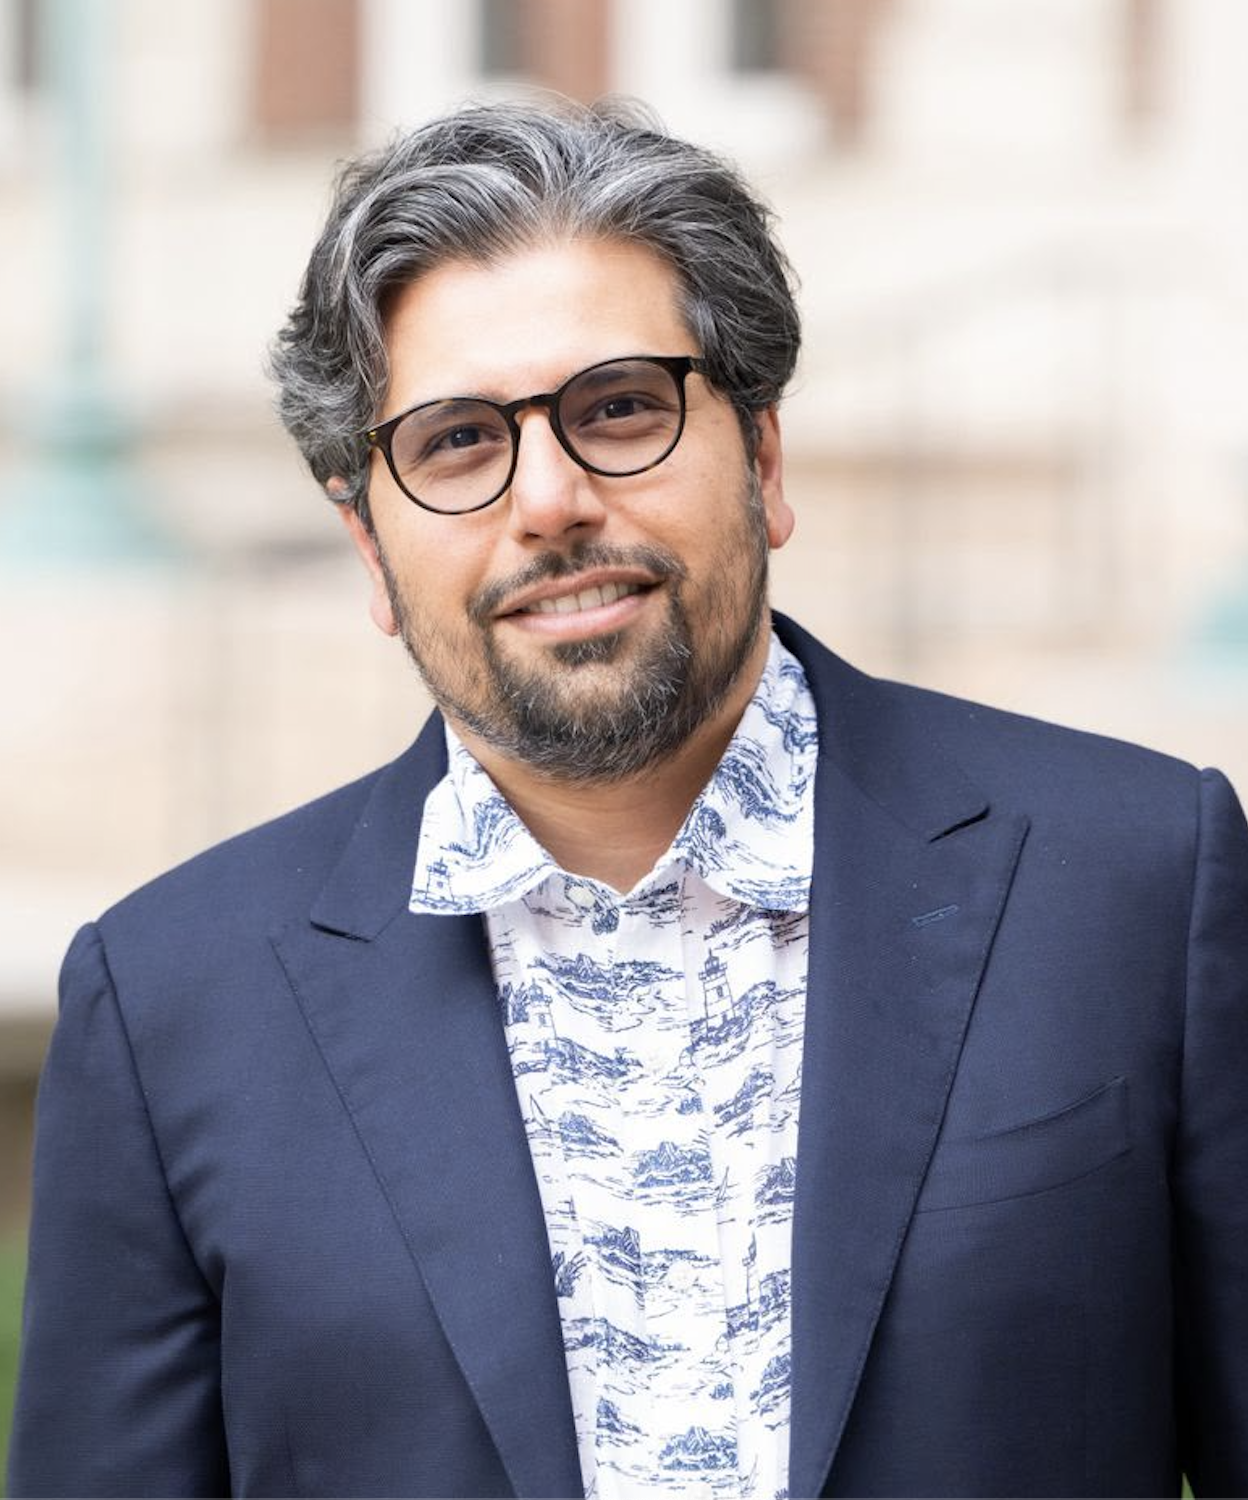
Suril Desai

Suril Desai

Featured
Crypto Policy CommentatorNishith Desai AssociatesNishith Desai Associates
India October 29, 2026 9 min readBy Bitnxt Editorial Team

Suril N. Desai on cutting India’s 1% crypto TDS, the limits of RBI power, why the e-rupee doesn’t remove trust, the industry’s own failures, and building self-custody that ordinary families can recover.

Tax & ComplianceBitcoinFounders
India Crypto Tax1% TDSRBISelf-CustodyBitcoinRegulation

Biography

Suril N. Desai is a commentator on India’s crypto policy and a vocal advocate for Bitcoin and self-custody. His view is that banks should earn people’s trust through service and accountability, and that regulation should protect citizens while allowing them meaningful alternatives.

In this Bitnxt Founder and Leader Interview Series Q&A, he examines India’s crypto tax regime, RBI powers, the e-rupee and UPI, token launches, and the industry’s own failures.

Interview Summary

Suril N. Desai on cutting India’s 1% crypto TDS, the limits of RBI power, why the e-rupee doesn’t remove trust, the industry’s own failures, and building self-custody that ordinary families can recover.

1

India Crypto Reality in 2026

Q1.If you could rewrite one clause of India’s crypto tax regime tomorrow, which would it be — the 30% flat tax, the 1% TDS, or the ban on setting off losses — and why that one?

I would cut the 1% TDS to 0.01%. It repeatedly locks up capital, even on losing trades. A later tax credit does not repair today’s cash-flow damage. The state already has reporting tools. It should collect information without choking liquidity and making compliance commercially punishing.

Q2.Estimates suggest roughly 70% of Indian crypto trading volume now happens offshore. Has the current regime protected investors, or simply exported them?

Investor protection cannot be measured by how much business disappears from India. The 70% estimate needs verification, but offshore migration is documented. When users move beyond effective local recourse, risk survives and domestic accountability weakens. I call that a policy failure dressed up as caution.

Q3.The RBI has reportedly leaned towards prohibition and pushed for banks to be walled off from crypto. How far can it realistically go?

RBI’s powers are subject to law and judicial review. The 2020 judgment demonstrated that by setting aside its banking restriction. Cutting off banking can strangle a business without banning it on paper. Any fresh restriction needs a lawful basis and must survive constitutional scrutiny; regulatory discomfort is not enough.

Q4.India still has no dedicated crypto law, yet exchanges must register with FIU-IND and follow PMLA. Is this “regulation by enforcement” workable long-term?

The state knows how to collect the tax and demand the data. Customers still need clarity about who safeguards their assets and what happens after an exchange fails. PMLA compliance matters, but it cannot substitute for a complete framework. Permanent uncertainty is a cost imposed on every serious builder.

Q5.If you were advising the RBI instead of the industry, what is the strongest argument you would make against crypto?

Monetary sovereignty, especially the risk of dollar stablecoins displacing rupees, is the strongest argument. Add leverage and links to banks, and financial-stability concerns become serious. But protecting the rupee and protecting banks from competition are different objectives. Regulators should show which risk each restriction addresses, and who pays the price.

Q6.Which part of the Indian crypto industry’s own behaviour has made regulators’ fears look justified?

Selling decentralisation while asking everyone to trust an opaque company. Reckless promotion and weak custody hand regulators their strongest argument. If you hold customer assets, prove what you hold and disclose what you owe. Calling yourself anti-bank means nothing if you reproduce the same dependency without accountability.

Q7.What is the realistic best case and worst case for Indian crypto policy over the next 24 months?

Best case: lower TDS, enforceable custody rules and banking access based on published criteria. Worst case: more financial exclusion presented as protection, with activity moving elsewhere. My base case is more reporting before meaningful reform. India risks supplying the talent while other countries become home to the businesses.

2

Money, Trust and the Future

Q1.You’ve argued the root problem with conventional money is how much trust it demands. Does the e-rupee fix that trust problem, or concentrate it further?

The e-rupee digitises sovereign money; it does not abolish trust in the sovereign. Programmable versions can attach conditions to spending. I want strong privacy, due process and the continued choice of cash. A faster payment is not greater freedom if somebody else gets more power over when and how you spend.

Q2.UPI is a global success story. Does it make Bitcoin less necessary in India — or does it make the case for open rails stronger?

UPI is excellent at moving rupees between accounts. It does not give you Bitcoin’s ability to hold an asset without a bank or central issuer. Faster banking does not settle who controls your money. India can celebrate UPI and still demand alternatives to compulsory dependence on financial intermediaries.

Q3.Bitcoin, stablecoins, CBDCs, tokenised assets — where does India’s money sit on that map in 2035?

I expect coexistence: rupees for daily life, CBDCs for some settlement, stablecoins where permitted, tokenised assets, and Bitcoin for self-custody. The real contest will be over control. Will Indians get meaningful choices, or merely different apps leading back to the same gatekeepers? That choice is a political question as much as a technical one.

3

For Builders and Founders

Q1.What is the single biggest legal mistake you see Indian Web3 founders make in their first year?

Treating the law as something to fix after the token sale. A white paper does not establish what you are legally selling, who controls the money or what buyers can claim. Work that out before launch. Otherwise you may be selling legal liabilities disguised as innovation.

Q2.Is there still a credible case for building a crypto company in India, or is “India talent, Dubai/Singapore entity” now the default playbook?

India should be able to export products without having to export its founders. There is a strong case for building here, especially software and infrastructure. Overseas incorporation may make commercial sense, but Indian tax and regulatory obligations can still follow. Policy should give founders reasons to stay beyond sentiment.

Q3.How should founders think about token launches given India’s current stance — is “no token” increasingly the safer default?

For many businesses, yes. A token should earn its place in the product. If its main job is to raise money before there is a business, I am sceptical. Its function and legal rights must be defensible. The word “utility” in a white paper is not a legal opinion.

Q4.In 2023 you argued the community needed one collective voice beyond exchanges. Three years later it still doesn’t exist. Whose fault is that — including the industry’s own?

Associations exist, including Bharat Web3 Association. My test is whether the agenda defends the user as vigorously as the exchange. We need positions on self-custody, privacy and lawful banking access, not just trading volumes. Public advocates, including me, have to help organise that work. Complaining is the easy part.

Q5.Where should Indian developers focus in 2026–27: Bitcoin infrastructure, stablecoins, real-world asset tokenisation, AI-crypto, or something else?

Build tools that make people less dependent on gatekeepers. My priorities are Bitcoin security, usable self-custody and recovery that ordinary families can manage. Stablecoin and tokenisation projects must explain the rights and redemption behind the token. Adding “AI” to “crypto” does not create a business model.

4

For Investors and Everyday Users

Q1.What is something most Indian crypto investors believe about the law that is simply wrong?

That the government collecting tax means the government guarantees the investment. FIU registration is not deposit insurance, a solvency certificate or blanket permission for every product. Learn exactly what is regulated. A registration badge should never do the thinking that a customer’s due diligence is supposed to do.

Q2.India starts sharing cross-border crypto data under the OECD’s CARF from April 2027. What should Indians holding crypto on foreign exchanges do before then?

India has not yet formally committed to the OECD’s CARF; its 14 September 2026 list still shows India as “not yet committed,” so April 2027 is a stated plan, not a confirmed exchange date. But a foreign exchange is not an invisibility cloak: Indian residents are taxed on worldwide income, so crypto gains made abroad are already taxable under India’s VDA rules. Reconcile every trade and wallet transfer across all exchanges now, make sure your ITR reflects them, and review overseas-asset disclosure and FEMA/LRS obligations with a CA familiar with crypto cases.

Q3.Self-custody versus exchange custody: from a legal and inheritance standpoint, what should Indians be thinking about?

Not your keys, not your coins. But if your family cannot recover those keys, your sovereignty can become their loss. Keep a will, an asset inventory and secure, tested recovery instructions; never put seed phrases in the will itself. With an exchange, understand your legal claim and its succession process.

Q4.What would you tell a 25-year-old Indian who wants to build a career in crypto, not just invest in it?

Learn a skill that survives a price crash. Code, audit, investigate, or understand the law well enough to solve real problems. Contribute work people can inspect. If your entire career disappears when a token falls 80%, you built your livelihood on somebody else’s marketing.

5

Closing Question

Q1.Bitnxt brings together founders, builders, investors and everyday crypto users. If you could leave this community with one suggestion — something to start doing, stop doing, or build next — what would it be?

Build self-custody that ordinary families can use and recover safely. If freedom requires technical expertise most people do not have, it will remain a privilege. Make control practical. The point of this technology should be that people can leave an intermediary without losing access to their money.

Key Takeaways

  • Desai would cut India’s 1% TDS to 0.01% because it locks up capital even on losing trades.
  • Offshore migration weakens domestic accountability rather than protecting investors.
  • RBI restrictions need a lawful basis and must survive constitutional scrutiny, as the 2020 judgment showed.
  • Founders should settle what a token legally is before launch; for many businesses “no token” is the safer default.
  • Self-custody holders should keep a will, an asset inventory and tested recovery instructions, never seed phrases in the will itself.

Rapid Fire Round

Q

Most overrated idea in crypto?

Decentralisation that requires permission from the CEO.

Q

India legalises and lightly regulates crypto by which year — or never?

Ownership is not blanket-banned today. The question is when India will make lawful participation workable. I want a clear framework; I will not invent a date to make policy paralysis sound like a timetable.

Q

One sentence you’d want every Indian policymaker to hear about Bitcoin?

Your job is to protect citizens from abuse, not banks from competition.

By Bitnxt Editorial TeamLast updated Oct 29, 2026

Want to be featured on Bitnxt?

Share your crypto journey, startup, product, investment insights, trading strategies, or blockchain innovation with thousands of readers worldwide.

  • Increase brand visibility
  • Build authority & credibility
  • Improve SEO with a permanent interview page
  • Reach crypto investors
  • Connect with potential partners
  • Showcase your products & innovations
  • Share your founder's vision
  • Reach media & journalists
  • Attract new customers
  • Grow your community
  • Build your personal brand
  • Gain long-term organic exposure

Bitnxt uses cookies to run the site, understand how it is used, and measure ads. You can accept or decline below, and change your choice any time in our Privacy Policy.