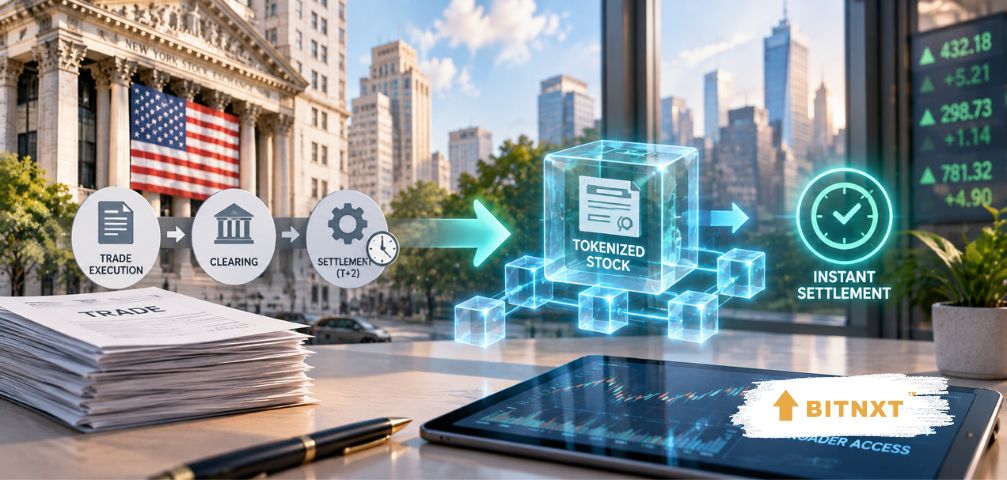
What settlement actually is
When you buy a share, two things have to happen: the seller delivers the security and the buyer delivers the cash. Settlement is the process of completing both. In US equity markets that currently happens on T+1 — one business day after the trade.
The gap exists for a reason, and understanding that reason is the whole subject.
During the settlement window, a central counterparty steps between the two sides. It novates the trade, becoming buyer to every seller and seller to every buyer, then nets everything down. Instead of settling thousands of individual obligations, participants settle net positions.
Netting is not administrative overhead. It is the mechanism that lets US equity markets clear trillions in trades while moving a small fraction of that in actual cash and securities.
The cost of that arrangement is counterparty risk. At T+1 there remains one business day during which a counterparty could default, markets could move, or an operational failure could disrupt settlement. That risk is managed through margin — collateral posted and held.
What atomic settlement does
Atomic settlement is the blockchain implementation of delivery versus payment. When both the asset and the payment exist as tokens, a smart contract verifies that both legs are present and executes the exchange in a single transaction. Either both transfers complete or neither does.
The benefits are real and worth stating plainly:
Principal risk is eliminated at execution rather than managed across a settlement window.
Margin and collateral posted against settlement exposure are freed, because there is no exposure period.
Reconciliation across fragmented intermediaries largely disappears, since both parties are looking at the same ledger entry.
Failed settlements become structurally impossible in the ordinary case — a trade either settles or does not occur.
SEC Chairman Paul Atkins has said that tokenization promises to achieve T+0 settlement and can reduce market risk and increase transparency. That is a genuine regulatory endorsement of the direction.
And what it costs
Here is the part that crypto coverage of this subject almost never includes.
Atomic settlement is gross settlement. Every trade settles individually, at full value, at the moment of execution. That means it eliminates netting — and netting is precisely what keeps liquidity requirements manageable.
SIFMA has put the point directly: multilateral netting significantly reduces the amount of cash and securities that must move at settlement, reducing required liquidity and margin, and settling every trade one by one at gross amounts would increase funding needs and costs.
T+1 netted settlement | Atomic gross settlement | |
|---|---|---|
Counterparty risk | Present for one business day, managed by a CCP with margin. | Eliminated at execution. |
Liquidity required | Low. Only net obligations move. | High. Every trade moves full value, both legs, immediately. |
Intraday flexibility | Participants can run an intraday deficit provided they acquire assets by end of day. | None. Assets must be present at the moment of trade. |
Settlement guarantee | The CCP guarantees settlement of netted obligations, reducing credit exposure. | No central guarantee; the guarantee is the atomicity itself. |
Scalability at volume | Proven at current US equity volumes. | Untested at those volumes; funding requirements scale with gross turnover. |
The intraday deficit row is the underrated one. Under the current model a broker-dealer can be short a security during the day so long as it is acquired by settlement. Remove that, and every participant must pre-fund every position — which means holding idle cash and securities that are currently deployed.
Academic analysis of the shift to T+0 has noted that requiring higher liquidity from broker-dealers could facilitate faster settlement but would leave them with less capital to invest, which is why the industry has not embraced it.
The finding that points to the middle
There is a useful piece of research that reframes this as an engineering question rather than an ideological one.
A study of post-trade netting found that netting over a window of about one hour delivers most of the benefits of full end-of-day netting.
If most of the netting benefit is available within an hour, the choice is not between T+1 and atomic. It is between T+1 and T+1 hour.
That is a genuinely different design target. Hourly batch settlement on a distributed ledger would compress counterparty exposure from a day to an hour while preserving the large majority of the liquidity efficiency. It is less rhetorically satisfying than instant settlement, and it is far more likely to be adopted.
SIFMA frames the whole question this way: settlement in US markets is a spectrum rather than a single design choice, and the right question is not whether one model displaces the others but how firms choose among complementary options suited to a given product, workflow and risk profile.
The cash leg is the actual bottleneck
Even where atomic settlement is desirable, it requires something most discussions assume rather than examine: tokenized money.
A tokenized security can move on-chain in moments. If the corresponding payment still travels through traditional banking rails, the transaction cannot be atomic — the two legs are on different systems with different timing and different finality.
So atomic settlement requires the cash leg to be a stablecoin, a tokenized deposit, or wholesale central bank money. That is why the tokenized deposit and bank stablecoin work matters more to settlement reform than the tokenized securities work does. The asset side was never the hard part.
It is also why an early DTCC pilot with the Digital Dollar Project, testing atomic settlement of tokenized securities against a simulated central bank digital currency, concluded that tokenized assets may improve asset management efficiency but would not necessarily deliver greater liquidity and risk benefits than existing reserve account settlement.
The finality problem, and the root wallet
One more obstacle that rarely surfaces in enthusiastic coverage.
Legal finality and technical finality are different things. Work under Project Guardian has noted that finality on a distributed ledger cannot depend solely on probabilistic consensus — a securities settlement system needs a moment after which a transfer is legally irreversible, and probability is not that.
There is also the awkward matter of corrections. Securities law requires that certain transactions can be reversed — fraud, error, court order, corporate action adjustments. The DTCC pilot handles this by requiring DTC to retain override capability through a root wallet for legally mandated corrections.
Sit with that for a moment. The settlement system’s immutability is deliberately subject to an administrator with reversal powers, because the law requires it. That is not a flaw in the design — it is what makes the design lawful. But it does mean the version of tokenized settlement that regulators will approve is not the trustless one.
Where the US actually is
Against all that, the current US implementation looks appropriately modest.
Following an SEC staff no-action letter in December 2025 permitting a three-year DTC tokenization pilot, and the SEC’s approval of Nasdaq’s rule change in March 2026, tokenized and conventional shares trade on the same order book with the same rights and the same T+1 settlement cycle. The token is minted post-trade: Nasdaq passes the instruction to DTC, which mints and delivers a token to a DTC-registered wallet and reconciles a control account in the background.
DTCC has targeted initial limited production trades in July 2026 with full launch planned for October, covering Russell 1000 constituents, ETFs tracking major indices, and US Treasury securities.
Settlement timing is unchanged. What has been built is optionality — the ability to move an asset between traditional book-entry form and tokenized form, without disturbing the clearing and settlement machinery underneath.
So what actually changes first?
Not equity settlement. Collateral.
WHERE THE NEAR-TERM VALUE IS The problem tokenization genuinely solves today is that the right asset is frequently in the wrong place at the wrong time. A tokenized money market fund share can be pledged, recalled and re-pledged in minutes rather than days, continuously rather than within business hours — without disturbing the underlying position. That is why DLT-settled repo and short-term funding reported average daily volumes of $339 billion in September 2025 and $385 billion the following month, while tokenized equity settlement remains a pilot. Collateral mobility has a measurable return in basis points on funding costs and reduced buffer requirements. Faster equity settlement mostly reallocates risk between participants. |
What to watch
Whether an intraday or hourly netting model emerges as the practical target, rather than atomic settlement. That would be the strongest signal the industry has resolved the liquidity trade-off sensibly.
Progress on the cash leg — tokenized deposits, bank stablecoins and any wholesale central bank settlement. Without it, atomic settlement is not available regardless of how the securities side develops.
Whether the DTCC service moves from July limited production to October full launch on schedule.
Take-up of the tokenization flag on Nasdaq. Approval without volume would mean the market does not yet value the optionality.
Any published analysis of gross versus netted liquidity requirements at realistic US equity volumes. That number would settle much of this debate.
The bottom line
Tokenization can change settlement, and the change worth having is not the one usually advertised. Instant atomic settlement is technically achievable and would eliminate counterparty risk — while requiring every participant to pre-fund every trade at gross value, in a market whose current design depends on not having to.
The realistic path is compression rather than elimination: shorter netting cycles on tokenized rails, a tokenized cash leg to settle against, and legal finality with a supervised override. Less dramatic than the pitch, and considerably more likely to be built.
Meanwhile the genuine wins are already happening one layer over, in collateral. That is where hundreds of billions a day are moving, and it is happening without changing how a single share settles.
Important
This article is general information about market infrastructure. It is not investment, legal or financial advice. Settlement mechanics, pilot programmes and regulatory positions described are current as at the date stated and may change; several initiatives referenced are at pilot or proposed stage and may be delayed or not proceed. Figures are drawn from third-party sources and official publications for the periods described.
Sources
SIFMA analysis of atomic settlement in equities markets, DTCC and Digital Dollar Project pilot materials, SEC approval orders and staff no-action relief, Project Guardian DvP guidance, Bank for International Settlements DvP models, University of Chicago Legal Forum analysis of T+0, plus reporting from Ledger Insights and Everstake.
Bitnxt tracks RWA platforms, tokenization infrastructure and market infrastructure providers across the US, UK, EU and Asia. Explore the directory at bitnxt.io.