Plenty has been written about why stablecoin payments are growing. Much less has been written about what actually happens inside a business that adopts them — which systems change, which team inherits the work, and what the auditor says in twelve months.
This is that version.
The economics that start the conversation
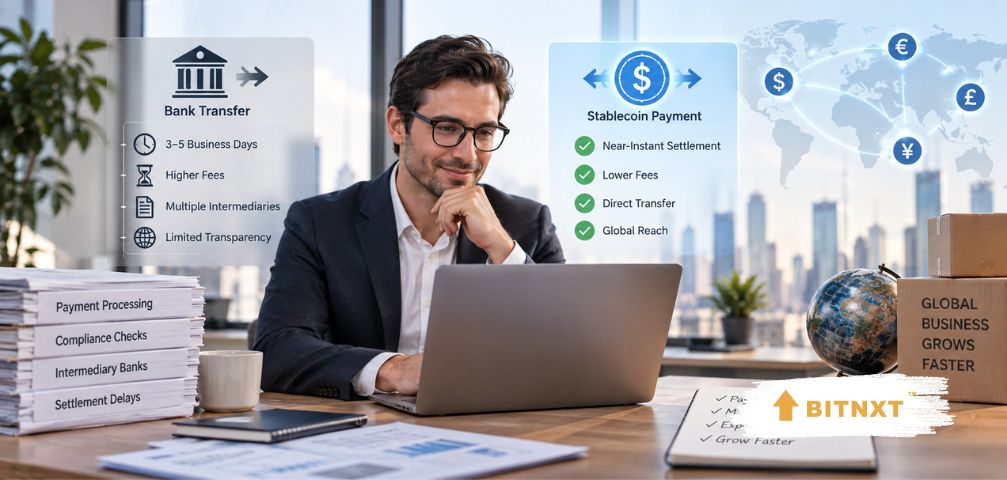
International payments can incur fees of 2–5% once correspondent bank charges, FX spreads and intermediary fees are counted, and those costs compound for businesses operating across multiple jurisdictions. Consumer remittance corridors run higher still, around 6.6% on average.
Then there is time. Traditional banking operates within cut-off times and business-day constraints, which creates liquidity gaps for companies managing treasury across time zones. A payment initiated Friday afternoon in one market may not land until Tuesday in another.
Against that, stablecoin settlement runs at roughly 0.5–2.5% all-in and completes in minutes, continuously. For a business making frequent supplier payments across borders, that is not a marginal improvement — it is a line item that changes materially.
The pitch is simple enough that it does not need embellishment. What needs explaining is everything that happens after the payment lands.
How it actually works — nobody touches a wallet
The most common misconception is that adopting stablecoin payments means your finance team starts managing private keys. In the standard enterprise flow, it does not.
Step | What happens |
|---|---|
1. On-ramp | The business funds a named virtual account in fiat. The provider converts to a regulated stablecoin. Know Your Business verification is completed at this stage. |
2. Settle across | The stablecoin moves across a compliance-screened network in minutes rather than days. |
3. Off-ramp or hold | Converted to local fiat at the destination, or held in stablecoin where the counterparty prefers it. |
This is the fiat-to-stablecoin-to-fiat pattern, and it is why adoption has been possible at companies with no crypto expertise whatsoever. From the outside it looks like a faster, cheaper international transfer. The token is an implementation detail of the rail.
Where businesses do take on direct exposure is step three — holding balances in stablecoin rather than converting immediately. That decision, more than anything else, determines how complicated this gets.
The problem your controller will raise
This is the section most vendor material skips, and it is the single biggest practical barrier to adoption.
Stablecoins do not automatically receive fair value treatment under ASU 2023-08. The accounting treatment depends on the specific rights and obligations attached to each stablecoin, and it could fall under several existing frameworks:
Possible classification | What it means | Status |
|---|---|---|
Cash equivalent | Balances stay in the cash flow statement and are presented as what they operationally are. | The treatment most treasurers want. But most auditors and the SEC have taken the position that stablecoins do not currently meet the threshold, because redemption depends on the issuer’s solvency and operational capacity — counterparty risk that a bank deposit does not carry. |
Financial instrument | Treated as a financial asset where the stablecoin represents a contractual right to receive cash. | Plausible for fiat-backed stablecoins with explicit redemption rights. |
Intangible asset | The default fallback, and the one that distorts reporting by presenting routine operational treasury activity as an intangible. | The outcome treasurers are trying to avoid. |
That is the trap. A treasury team adopts stablecoins to make payments cheaper, and the finance team discovers that a balance sitting on the books for a week may not be presented as cash.
There is movement. FASB has added a research project to its agenda exploring whether certain digital assets should be classified as cash equivalents, with draft guidance expected around mid-2026 and potential implementation for 2027 financial statements. Until that lands, classification is a judgement your auditor will want documented.
The practical mitigation is straightforward: if you convert on receipt rather than hold, the classification question largely disappears. Businesses that treat stablecoins purely as a transit rail have a much simpler reporting position than those using them for treasury.
What the auditor will ask for
Proof of control — typically signed messages from the relevant wallet addresses.
Reserve confirmation obtained directly from the issuer or custodian.
Full transaction history with justification for how each item was classified.
A documented risk assessment covering counterparty, smart contract and regulatory exposure.
One further consideration: general accounting firms often lack the technical expertise to evaluate digital asset controls properly. Companies holding substantial balances are advised to bring in specialists for year-end work, which is a real cost to factor into the savings calculation.
Tax and reporting
The obligations differ by jurisdiction, but in the US the pattern is now reasonably clear: realised gains and losses reported on Form 8949 schedules, yield income on Schedule B or equivalent, and preparation for 1099-DA reconciliation against broker-reported data beginning with 2026 transactions.
Cross-border operations add another layer — KYC and AML records and transaction logs sufficient to satisfy both Travel Rule and CARF requirements in every jurisdiction where you operate.
None of this is prohibitive, but it is work that did not exist when you were sending a wire. Budget for it.
The risks you did not have with a bank transfer
Risk | What it means in practice |
|---|---|
Irreversibility | On-chain settlement is generally final. There is no chargeback, no recall, no correspondent to call. A payment to a wrong address is gone. |
Issuer and reserve risk | You are exposed to the issuer’s solvency, reserve quality and redemption capacity. This is precisely why auditors resist cash-equivalent treatment. |
Counterparty and provider risk | Operational failures interrupting settlement or redemption, regulatory enforcement restricting activity, or governance weaknesses at your payment partner. |
Cybersecurity | Wallets, private keys, smart contracts and infrastructure become part of your attack surface, even in custodial arrangements. |
Regulatory change | Licensing and supervisory requirements are still moving. 73% of businesses cite regulatory ambiguity as their top concern when adopting digital assets. |
The irreversibility point deserves emphasis because it inverts a control most finance teams rely on. Traditional payments are slow partly because they are reversible — the delay is where errors get caught. Removing the delay removes the safety net, which means the controls have to move upstream into approval workflows and address whitelisting.
The compliance model is different, not lighter
Stablecoin payments do not reduce compliance obligations. They relocate them.
Wallet issuance typically occurs before account opening, which is the reverse of traditional banking sequencing.
Sanctions screening extends beyond individuals, entities and locations to wallet addresses themselves.
Monitoring follows wallet activity throughout its lifetime rather than being a point-in-time check.
On the issuer side, the GENIUS Act framework requires one-to-one reserve backing consisting of cash, Federal Reserve deposits or Treasury bills maturing within 93 days, prohibits rehypothecation and commingling of customer funds, and mandates monthly public disclosures with management certifications. That gives a corporate counterparty something concrete to diligence — which is exactly what was missing before 2025.
A phased rollout that does not create rework
Start with one corridor. Pick the route where your current costs are highest and volumes are predictable. Prove the economics on a single lane before touching anything else.
Choose established partners. Custodians, payment platforms and compliance software that already serve enterprise clients — not the cheapest quote.
Write the policy before the first payment. Authorisation rules, conversion timing, exposure limits and address whitelisting. Retrofitting governance after volume grows is where rework comes from.
Default to converting on receipt. Hold balances only where there is a specific reason, and get the accounting treatment agreed with your auditor before you do.
Wire the data into your existing systems. Transaction data should flow directly into your ERP or treasury platform. A parallel spreadsheet is a reconciliation problem waiting to happen.
Form a cross-functional team. Finance, legal, IT and operations together — this touches all four, and a treasury-only pilot will stall at the audit.
Who this genuinely suits — and who it does not
Strong fit: businesses paying suppliers across borders regularly, particularly into markets where correspondent relationships are thin or expensive; companies with time-zone-driven liquidity gaps; firms already dealing with 2–5% all-in payment costs.
Weaker fit: domestic-only operations where instant payment schemes already work well; businesses with low cross-border volume where the compliance and accounting overhead exceeds the savings; companies without the finance capacity to document a new asset classification.
The honest test is volume times spread. If the annual saving does not comfortably exceed the cost of the additional accounting, audit and compliance work, this is not yet worth doing — and there is no shame in waiting for FASB guidance to land.
The bottom line
Businesses are switching because the arithmetic is compelling and, since 2025, the regulatory position on issuers is clear enough that a counterparty can be diligenced properly. Cutting a 2–5% cost to under 1% and days to minutes is not a marginal gain for anyone paying suppliers internationally.
But the switch moves work rather than eliminating it. Payment operations get simpler; accounting, audit and compliance get harder. The companies doing this well are the ones that treated it as a finance transformation project rather than a payments upgrade — one corridor, established partners, policy written first, conversion on receipt by default, and the auditor consulted before rather than after.
Do that and the savings are real and durable. Skip it and you will find out at year-end how your auditor classifies the balance sitting in your wallet.
Important
This article is general information only. It is NOT accounting, tax, legal or investment advice, and it is not a substitute for professional guidance on your own circumstances. Accounting treatment, tax obligations and regulatory requirements vary significantly by jurisdiction, entity type and the specific stablecoin used, and several relevant standards remain in development — including FASB guidance expected during 2026. Cost figures are indicative ranges from third-party research and will differ by corridor, volume and provider. Consult qualified accounting, tax and legal advisers before adopting stablecoin payments.
Sources
Guidance and research from FASB materials on digital asset classification, GENIUS Act requirements, the Association for Financial Professionals, Stripe, Tazapay, AlphaPoint, FS Vector, Dotfile and specialist digital asset accounting practices.
Bitnxt tracks stablecoin issuers, payment gateways and licensed service providers across the US, UK, EU and UAE. Explore the directory at bitnxt.io.